Can Financial Markets Put a Price on Central Bank Independence?
Central bank independence can sound like a constitutional or political question. For financial markets, however, it has a much more practical significance.
Central bank independence can sound like a constitutional or political question. For financial markets, however, it has a much more practical significance.
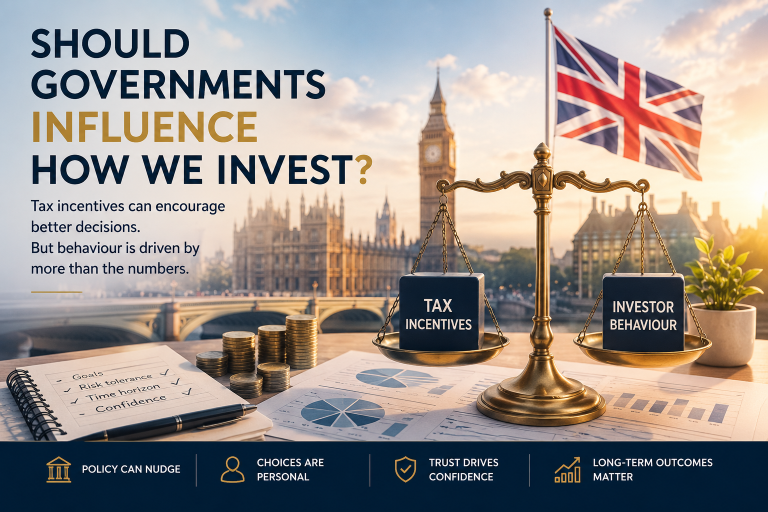
For decades, governments have used tax policy to encourage certain financial behaviours. Pension contributions receive tax relief, Venture Capital Trusts and Enterprise Investment Schemes offer generous incentives, and ISAs have encouraged millions to save and invest tax-efficiently.
This isn’t just a potential bailout, it’s a signal.
At first glance, the UK government’s move towards fully nationalising British Steel looks like a familiar story: a struggling industrial asset, mounting losses, and state intervention as a last resort.
When British Cycling quietly announced it would demerge its commercial unit, and open the doors to external investment, it didn’t grab the usual headlines. However, for professional investors tracking the evolution of sport as an asset class, the move is more than novel – it’s a signal.
Headline inflation in the UK is trending down, and the headlines are celebrating. But beneath the surface of this improvement lays a policy shift that risks distorting more than just the data. Earlier this year, the UK government removed the green energy levy from household energy bills – a politically popular move in a cost-of-living crisis. Instead of disappearing, those costs have been shifted into general taxation.
Every market shock seems to revive the same post-mortem: where were the regulators?
Yet as innovation accelerates across financial services – from decentralised finance to algorithmic execution – a more nuanced question emerges: When should regulation step in?
In global economic circles, one question keeps returning with greater urgency: Has the United States become too powerful or has the rest of the West simply become too reliant?
The Financial Conduct Authority (FCA) has just unveiled a landmark overhaul of short-selling rules in the UK, and it’s raising as many eyebrows as it is cheers. Under new proposals, the identity of investors betting against UK-listed stocks will no longer be publicly disclosed. Instead, the FCA will publish only anonymised and aggregated short positions.
In an age of hyper connectivity, the nature of economic risk is shifting, and fast. Gone are the days when corporate Darwinism, the principle of survival of the fittest, could be relied upon to sort winners from losers. Today, a well-placed cyberattack or technological disruption can destabilise a multi-billion-dollar enterprise overnight – with ripple effects that can threaten not just shareholder value but national economic stability.
As Adrienne Harris steps down as head of New York’s Department of Financial Services (DFS), she leaves behind a provocative idea: crypto passporting between the US and UK. For institutional investors and financial services firms on both sides of the Atlantic, it could be a transformational shift or another regulatory mirage.